
Why it works
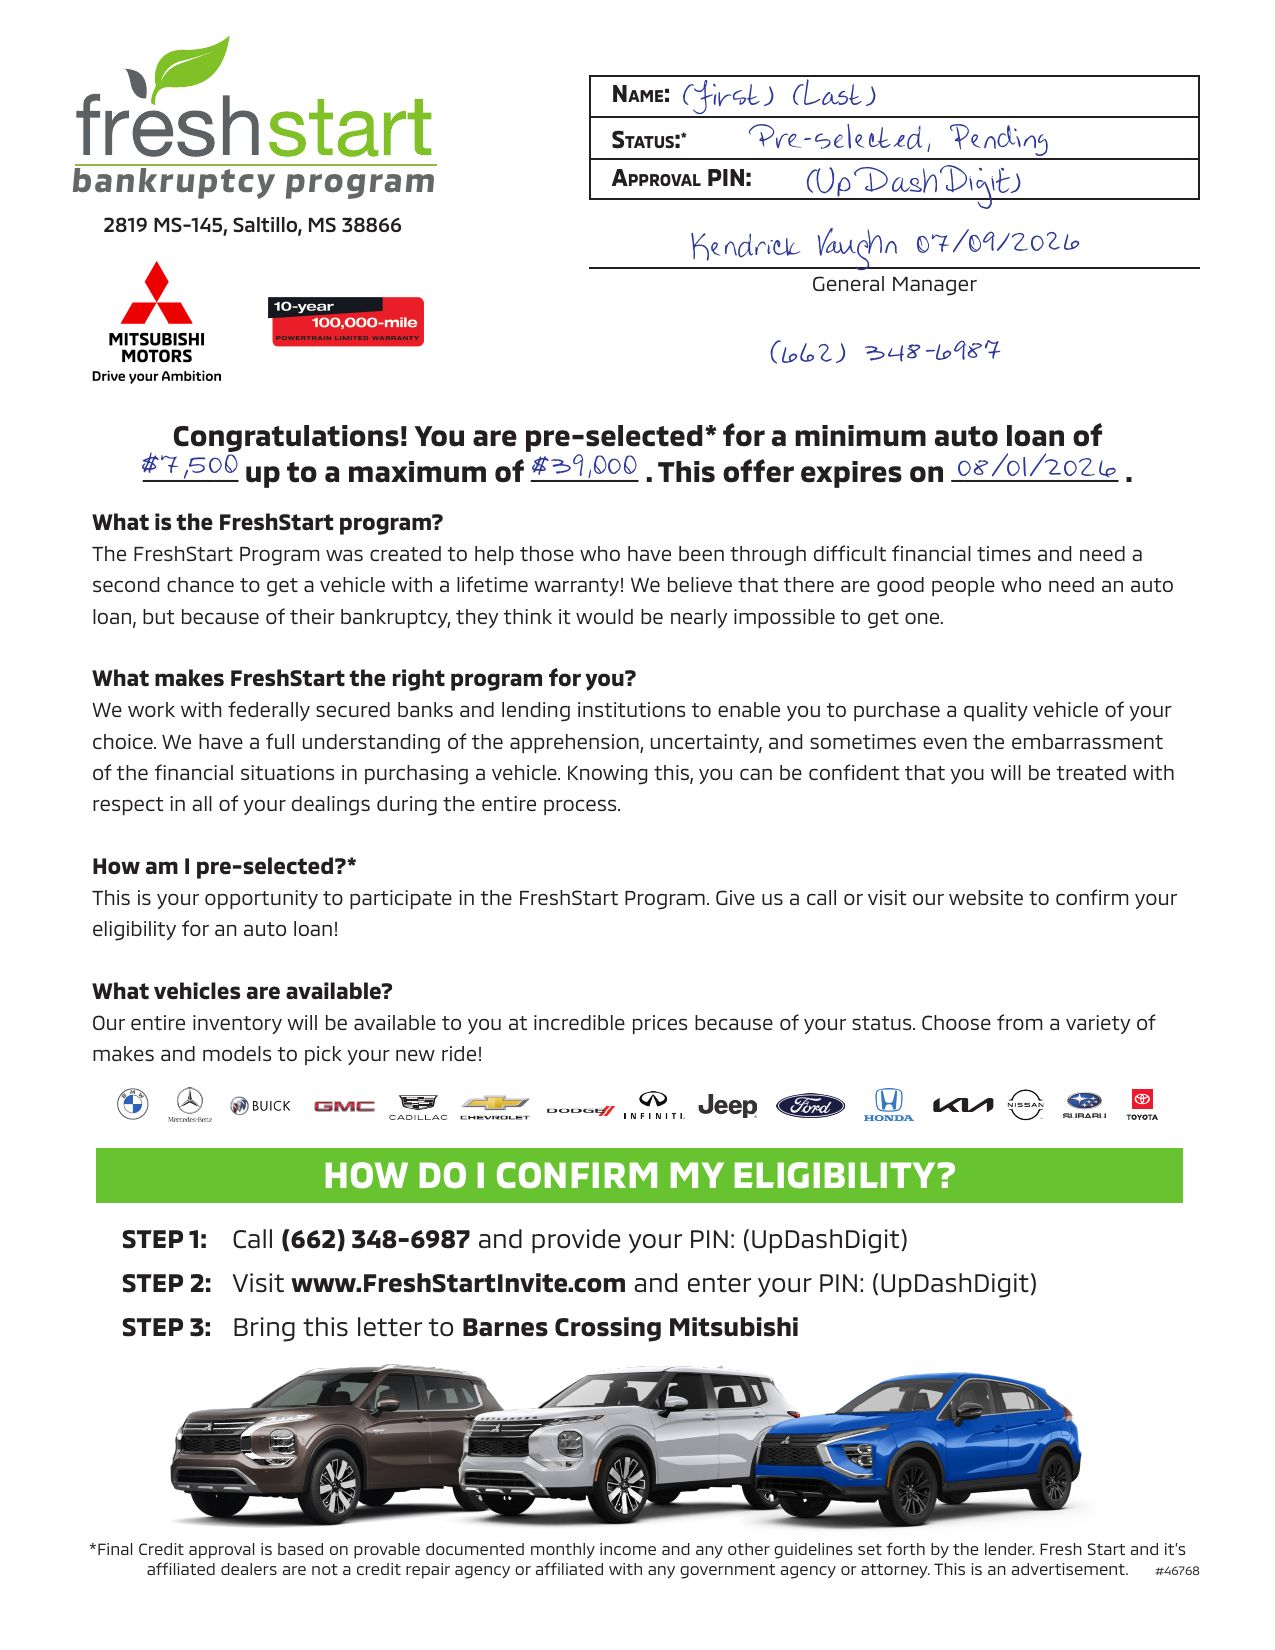
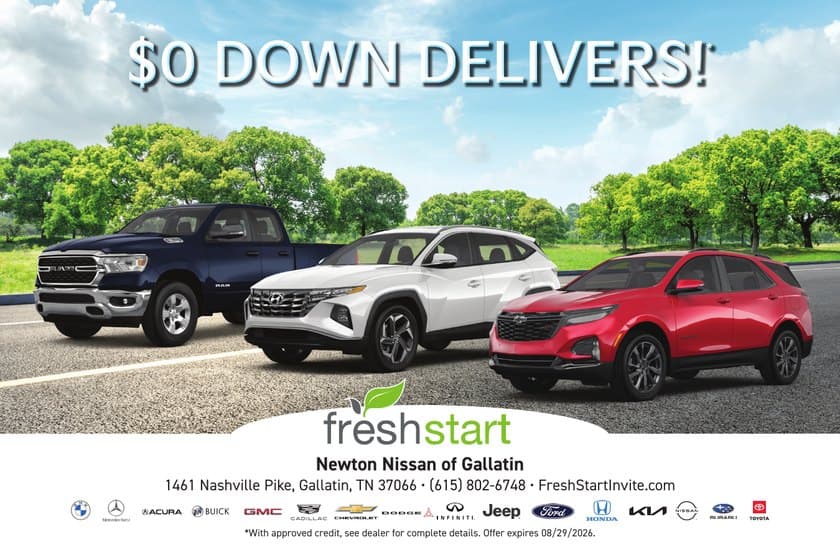
Credit-challenged buyers often assume they'll be turned away, so a piece that says plainly "you qualify for a program built for this" gets read. The Fresh Start creative is built around that:
- A clear, dignified message — what the program is and who it's for, without shame or hype.
- A personal status card — the recipient's name, a pre-selected status and a program bonus — that makes the offer feel real.
- A simple next step and a financing path the store has ready, so the response turns into a deal.
3 weeks outPostcard
Prescreen or bankruptcy-discharge criteria set and the list pulled; firm-offer terms and disclosures written.
10 days outPostcard
Each piece personalized — name, status, program bonus — and printed.
In-homePostcard
The Fresh Start postcard, letter or Snap Pak lands.
Same week
Calls and texts worked as they come in, with the finance path ready.
30 / 60 / 90 days
UpDash matches the mailed list to DMS sales at stores with a DMS feed.
Who gets it — and the rules that come with it
Lists come from credit-bureau prescreen criteria or bankruptcy-discharge data. A prescreened offer must be a firm offer of credit and carry the federal opt-out notice under the Fair Credit Reporting Act (how prescreened credit mail works), and any payment, down payment or rate shown triggers Truth in Lending disclosures. Every piece is reviewed against those before it prints. See credit-data mail for the full product.
Measuring it honestly
Response is the strong number here: the runs below drew responses from 8% to over a third of the households mailed. Sold units are harder to count because many of the stores that run Fresh Start don't have a DMS feed connected — only 10 of the 30 campaigns in 2026 did — so the sold total below is a floor, not the full picture.
Frequently asked questions
What is a Fresh Start car dealership campaign?
Mail aimed at credit-challenged buyers, including people recently discharged from bankruptcy, inviting them into a financing program built for their situation. It's usually sent to a prescreened or bankruptcy-discharge list and carries the legally required disclosures.
Is it legal to mail people who recently filed bankruptcy?
Yes, within the rules. Lists built from credit-bureau prescreening must be firm offers of credit with the FCRA opt-out notice, and any payment or rate shown requires Truth in Lending disclosures. Pieces should be reviewed for compliance before they print.
Why is the response rate on Fresh Start mail so high?
Because the audience is used to being ignored or turned down. A clear, respectful offer from a store that wants to work with them stands out — the 2026 runs above drew responses from 8% to over a third of the households mailed.
By Xcel Media Group · · Plain-text version