
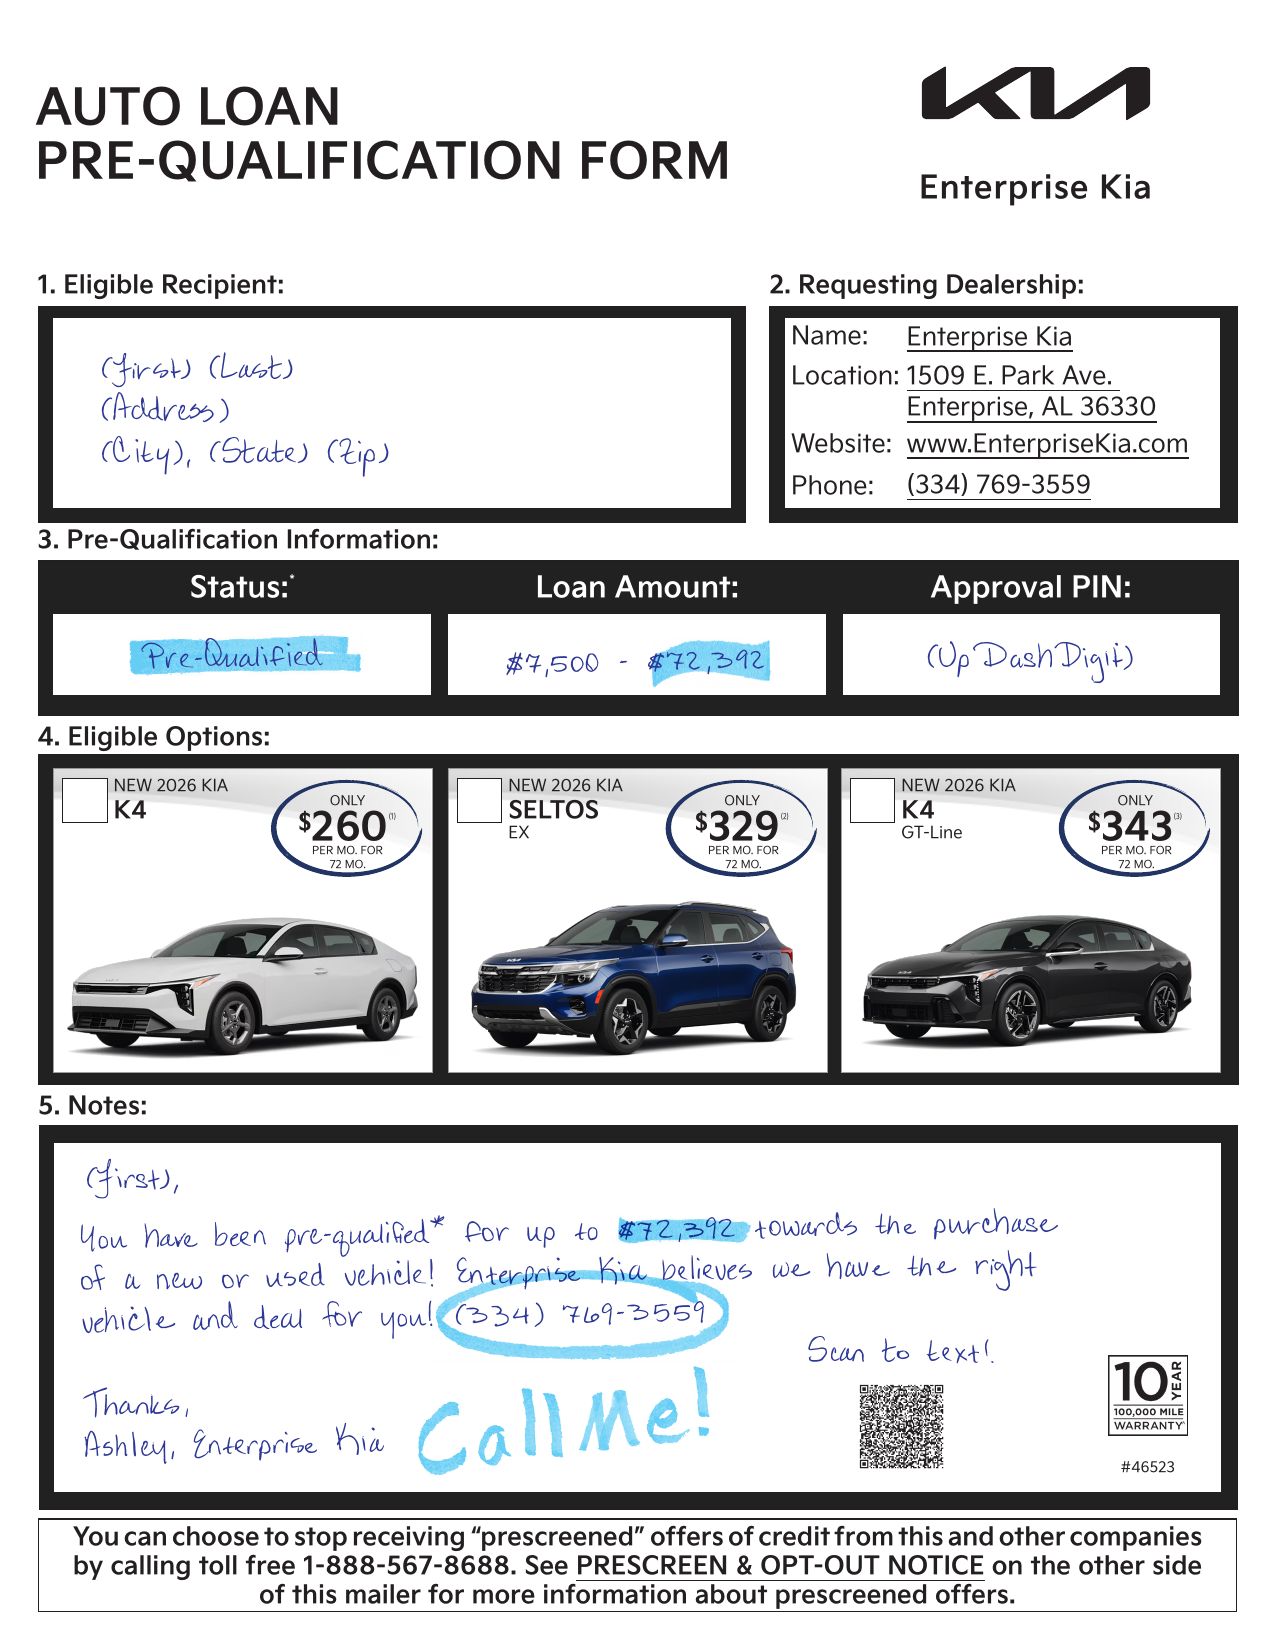
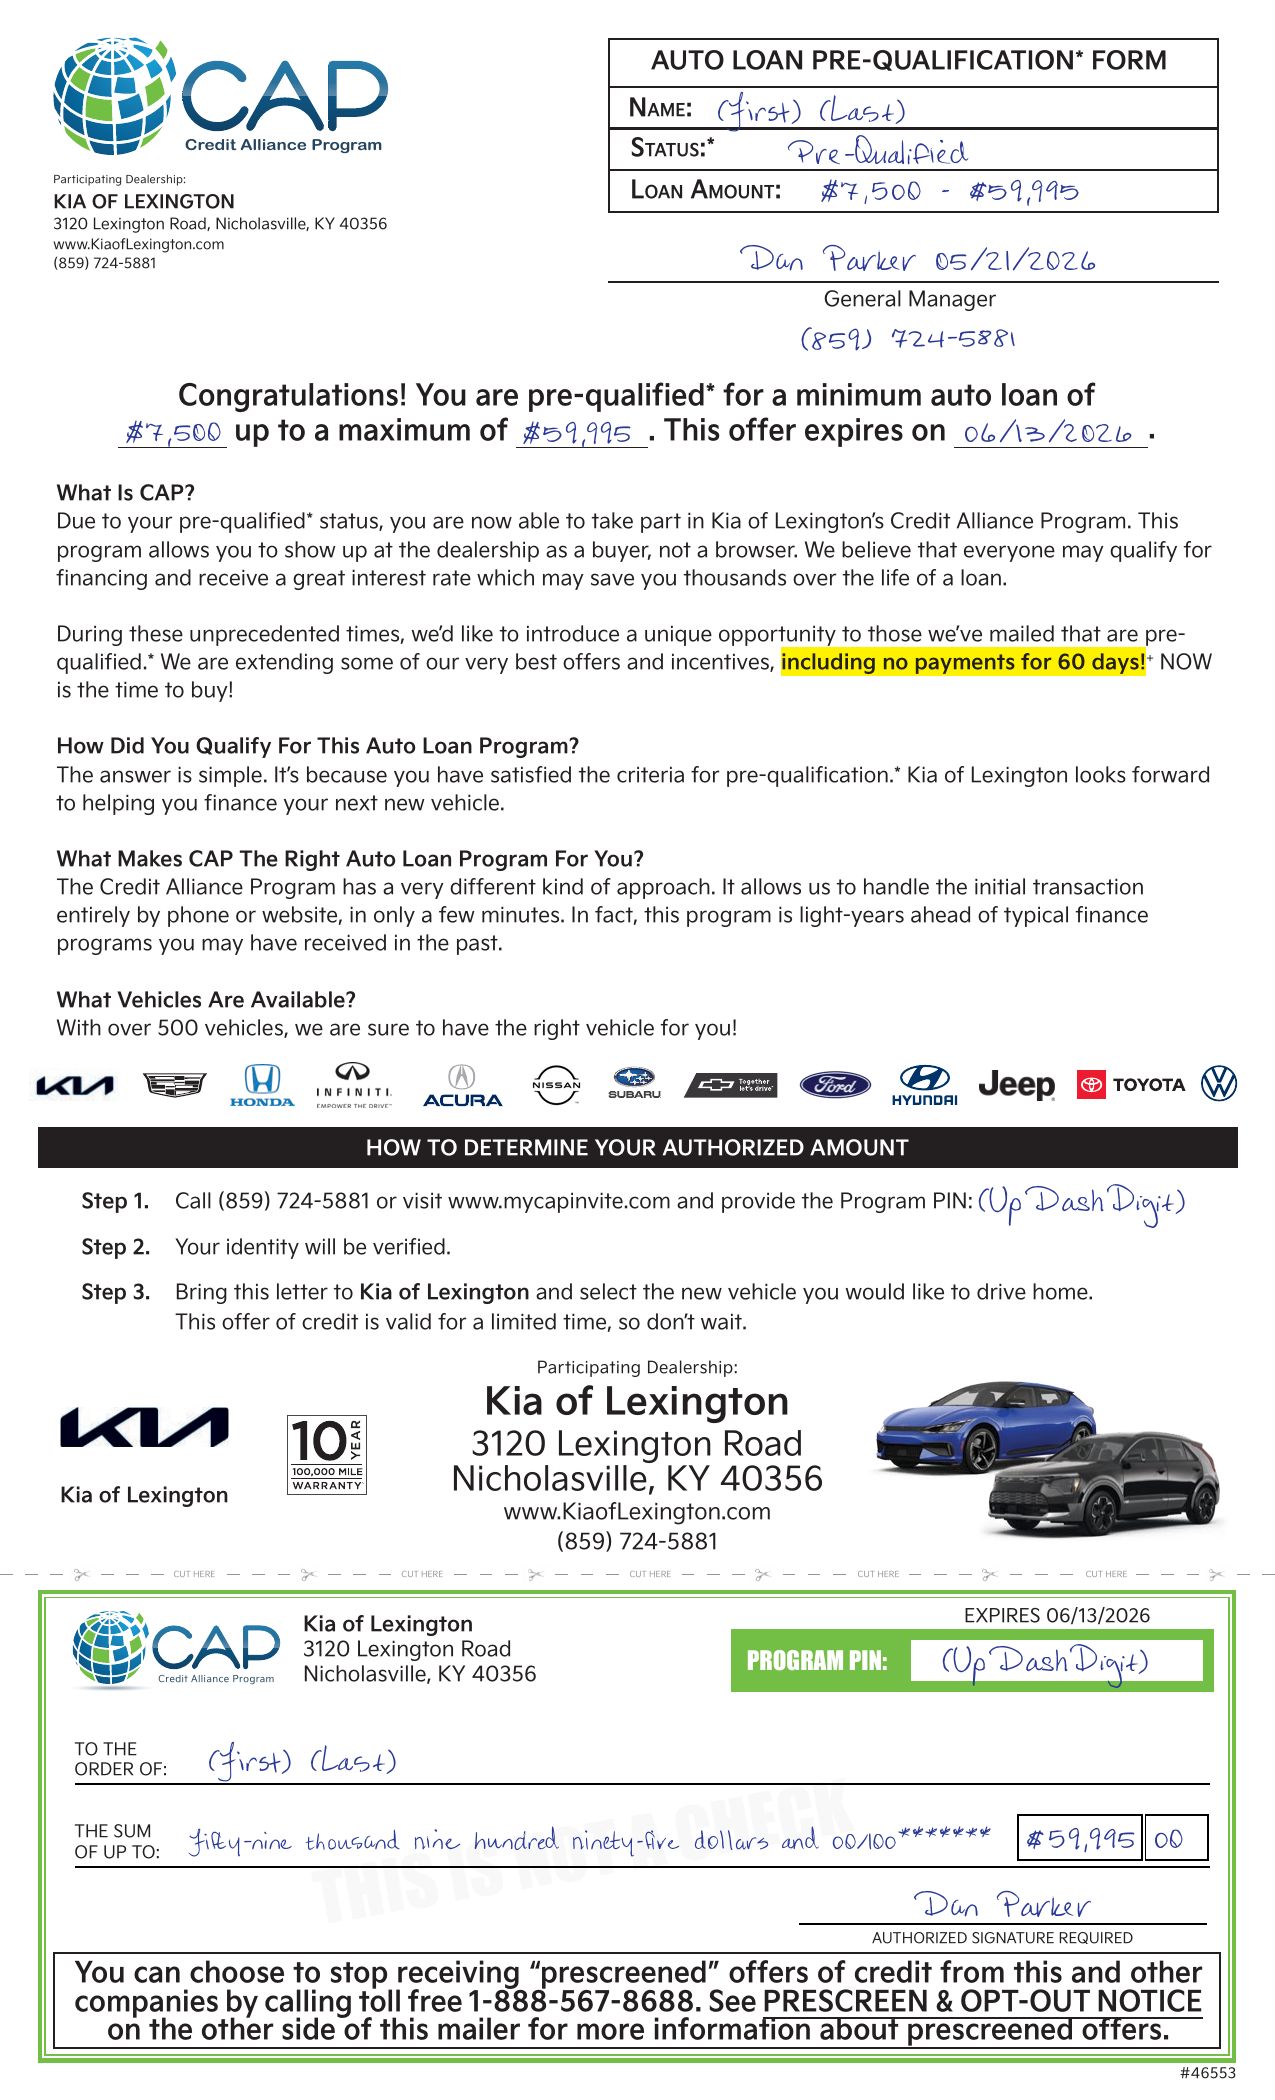
Why it works
Many shoppers don't come in because they're not sure they'll be approved. This piece answers that first:
- A firm offer, in writing — pre-qualified for a stated range, with an expiration date.
- A form that feels official — name, status, loan amount and approval PIN filled in, signed by the general manager.
- A voucher or check-style panel that makes the offer tangible.
- Three steps — call or go online with the PIN, verify identity, bring the letter in.
The rules that come with it
These lists are built from credit-bureau prescreen criteria, so every piece must be a firm offer of credit and carry the federal opt-out notice required by the Fair Credit Reporting Act — the "You can choose to stop receiving prescreened offers" panel on every Xcel piece (how prescreened credit mail works). Payment examples and rates trigger Truth in Lending disclosures. See credit-data mail for the full product.
How the channels work together
The letter carries the offer and the PIN. Most 2026 runs were mail only; some stores add text follow-up to customers who've opted in. Every call, text and web visit with the PIN is tracked in UpDash, so the finance office sees who's coming and why. After the campaign, the mailed list is matched to DMS sales.
3 weeks outLetter
Prescreen criteria set with the store's lenders; firm-offer terms and disclosures written.
10 days outLetter
Each letter personalized — name, pre-qualified range, PIN — and printed.
In-homeLetter
The CAP letter, voucher or pre-qualification form lands.
Same week
PIN calls and web visits go straight to the finance team; text follow-up where customers have opted in.
30 / 60 / 90 days
UpDash matches the mailed list to DMS sales and service.
Frequently asked questions
What is a CAP letter for car dealerships?
CAP stands for Credit Alliance Program. It's a prescreened credit offer that tells the consumer they're pre-qualified for an auto loan within a stated range, with a program PIN and steps to claim it at the dealership.
Is a pre-approval mailer a firm offer of credit?
It has to be. Lists built from credit-bureau prescreening may only be used for a firm offer of credit, and the piece must include the FCRA prescreen opt-out notice. Final terms still depend on the lender's verification.
What response should a dealership expect from pre-approval mail?
It varies with the list and offer. The strongest 2026 runs above drew a 3–4% response; a larger, broader list drew less response but more DMS-matched sales in total.
By Xcel Media Group · · Plain-text version